
Three of the most closely watched chip stocks are trading at very different valuations, and Morningstar’s latest read on all three says the market has mispriced at least two of them.
AMD has closed the gap with its fair value estimate, while Nvidia and Intel still look undervalued by a significant margin. That gap is not a simple buy signal. It raises the question of which company is best positioned as AI spending shifts from raw training power to something more complex.
Morningstar raised its AMD fair value estimate to $570, putting the stock roughly at fair value with about 18% implied upside. Nvidia carries the largest discount of the three, with roughly 50% implied upside to its fair value target, while Intel shows about 40% implied upside. Morningstar assigns all three a “Very High” uncertainty rating, meaning the spread between the bull and bear cases remains wide.
AMD posts a record quarter on data center strength
AMD delivered its strongest quarter on record in the three months ended September 30. Total revenue came in at $13.38 billion, up 45% year over year, driven almost entirely by data center demand. The data center segment alone posted $8.5 billion in revenue, up 97% from a year earlier as hyperscalers accelerated spending on AMD’s Instinct MI450 GPUs and EPYC server processors, according to AMD.
Also read: AMD CEO Su shares important supply news with stock market investors
Non-GAAP diluted earnings reached $2.09 a share, up 74%, while gross margin expanded to 56%. The company guided fourth-quarter revenue to roughly $17 billion, plus or minus 3%. AMD’s data center business now accounts for 58% of total revenue, up from 42% a year earlier.
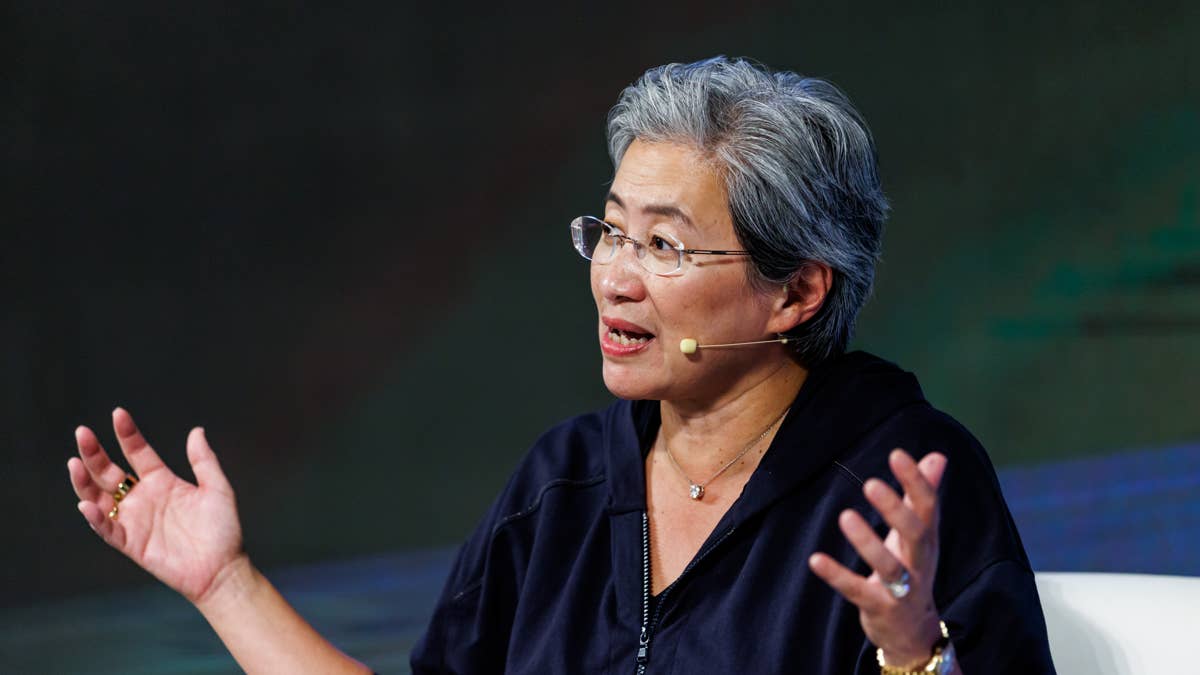
On the earnings call, CEO Lisa Su said AMD now expects data center revenue to more than double year over year in 2027, a forecast that marks an upgrade from earlier guidance of more than 80% growth issued before the Q3 results.
AMD shares were down about 2.6% in premarket trading on November 5, extending a broader pullback in chip stocks. The Nasdaq was also lower by roughly 1.6%.
The Anthropic deal anchors AMD’s AI ambitions
AMD’s biggest strategic commitment in 2026 was not a product launch but an investment. The company announced a partnership with Anthropic valued at up to $5 billion, covering 2 gigawatts of AMD Instinct GPU compute and a collaboration on ROCm, AMD’s open-source software stack for AI workloads. The first gigawatt of capacity is expected to come online in the first half of 2027, according to AMD.
Meta and OpenAI have each separately committed to 6 gigawatts of AMD GPU capacity, pushing AMD’s total announced deployment commitments to roughly 14 gigawatts across its three largest AI customers. Those commitments reflect a broadening of the customer base that AMD has been building since it launched its MI300X accelerator last year.
The software gap remains AMD’s most discussed risk. Nvidia’s CUDA platform has a decade-long head start on AMD’s ROCm, with a larger library of tools, optimized models and developer workflows.
Switching costs are real for companies already deep in the Nvidia ecosystem. The Anthropic ROCm collaboration is AMD’s most visible effort to close that gap, but analysts widely acknowledge the distance is still significant, according to AMD.
Musk’s SpaceX deal underscores Nvidia’s lock on big buyers
Nvidia’s moat was most evident in a deal disclosed in August 2026. Elon Musk said SpaceX would use Nvidia chips exclusively in its data centers, a decision that helped underpin the company’s $40 billion GPU financing deal with Apollo Global Management.
That commitment, the largest committed GPU financing ever announced, illustrated the kind of anchor customer Nvidia can attract that AMD still struggles to match in head-to-head competition at the largest scales of spending, according to SpaceX.
Nvidia reported second-quarter fiscal 2027 revenue of $96.2 billion earlier this year, up 106% year over year, with data center revenue reaching $89 billion. The company also said it has visibility into nearly $20 billion in total server CPU revenue this fiscal year as it pushes its Vera chip into the CPU market alongside its GPU business.
Intel’s quarter beats but its guide falls short
Intel reported third-quarter revenue of $16.5 billion on October 30, up 21% year over year. Data center and AI segment revenue climbed 78% to $7.3 billion, reflecting accelerating demand for server processors. The stock fell 29% the day results were released, however, after fourth-quarter guidance of $15 billion to $16 billion came in well below the roughly $17 billion Wall Street had expected, according to Intel.
More Wall Street:
- Nvidia and Micron are about to lord their successes all over Wall Street
- Nvidia, Palantir, and Alphabet send waves through Wall Street
- Wall Street elites will pocket windfall from record $46 billion profits
Bank of America analyst Vivek Arya followed the report with a downgrade, cutting Intel to Neutral from Buy and reducing his price target to $100 from $145. Arya wrote that Intel is “not yet technically competitive” in AI accelerators, a gap he said is wide enough to limit how quickly the company can capture the data center spending surge that has lifted AMD and Nvidia, as reported by TheStreet.
Intel CFO David Zinsner said the company expects server CPU market share to remain above 30% in both 2026 and 2027, while CEO Lip-Bu Tan framed Intel’s foundry business as a long-term opportunity that the company is building carefully rather than aggressively. The stock’s sharp post-earnings decline reflected how little margin for error the market is giving Intel as AMD continues to gain ground in its core server processor market.
The PC slowdown hits AMD and Intel equally
Both companies are dealing with a deteriorating personal computer market on top of their data center ambitions. Gartner reported that worldwide PC shipments declined 22.4% in the third quarter of 2026 as component cost inflation raised average selling prices and pushed buyers to the sidelines.
AMD’s client and gaming segment fell 8% in the quarter, with gaming revenue dropping to roughly $800 million from $1.3 billion a year earlier. Lisa Su said on the earnings call that AMD’s planning assumption for 2027 is that the PC market will be “double-digit percentage down,” though she added the company expects its own client revenue to hold up better than the overall market through its Ryzen lineup and growing commercial adoption.
Intel faces the same headwind, with both companies dependent on a PC market that is shrinking faster than the data center market is growing for either company. The Gartner decline underscores why analysts keep returning to data center execution as the only metric that matters for either stock over the next 12 to 18 months.
Related: Microsoft just gave Nvidia shareholders a reason to pay attention